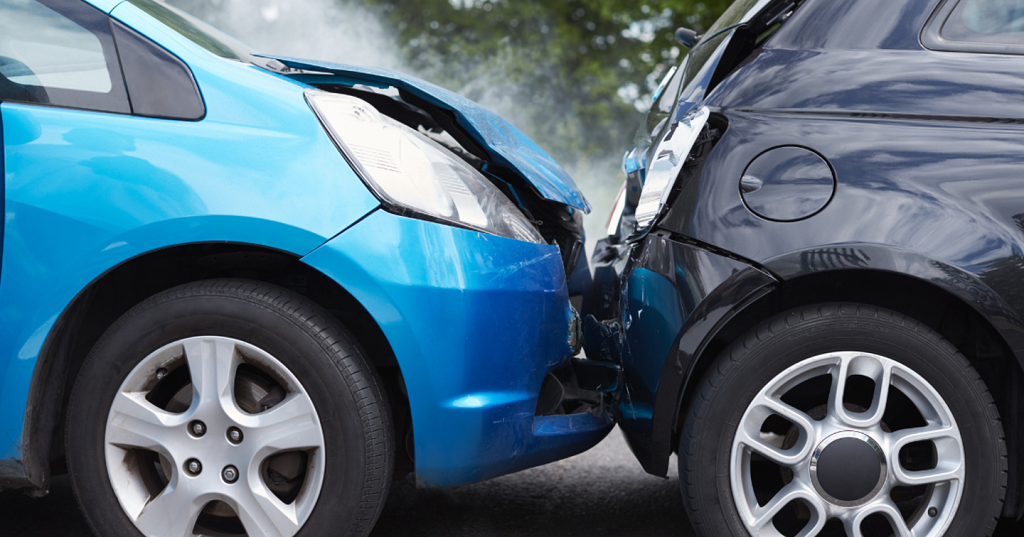
For many car owners, car insurance feels like a necessary evil. It’s a mandatory expense that can leave you wondering, “Why is this so expensive?” Unlike groceries or gas, the cost of car insurance isn’t readily apparent and can vary significantly from person to person. But fear not, gearheads and everyday drivers alike! This article unravels the mystery behind car insurance costs, empowering you to make informed decisions and potentially snag some savings.
Behind the Curtain: Factors Influencing Your Premium
Insurance companies aren’t out to fleece you (well, not usually). They base their rates on a complex risk assessment, considering several factors that determine how likely you are to file a claim. Here are the key players:
- Driver Profile: Age is a big one. Younger drivers, especially those under 25, are statistically more likely to get into accidents, leading to higher premiums. Gender used to be a factor, but many insurers no longer consider it due to fair-pricing regulations.
- Driving Record: Accidents, speeding tickets, and DUIs are red flags for insurers, signaling a higher risk of future incidents. A clean driving record translates to lower premiums.
- Location, Location, Location: Where you live significantly impacts your car insurance cost. Urban areas with higher traffic congestion and crime rates translate to pricier premiums compared to rural areas.
- Your Car: The make, model, and year of your car play a role. High-performance vehicles, sports cars, and luxury cars are generally more expensive to insure due to their repair costs and potential for theft.
- Your Coverage: The type and amount of coverage you choose directly affects your premium. Comprehensive and collision coverage provides more protection but costs more. Opting for higher liability limits or lower deductibles will also increase your premium.
Beyond the Basics: Additional Cost Considerations
While the factors above are the mainstays, some lesser-known elements can influence your car insurance:
- Your Credit Score: In some states, your credit score can be used to determine your insurance rate. A good credit score often translates to a lower premium.
- Your Commute: How much you drive and for what purpose (e.g., commuting vs. leisure) can affect your rate.
- Annual Mileage: Higher annual mileage indicates a greater risk of accidents, potentially leading to a higher premium.
- Modifications: Aftermarket modifications to your car can impact your insurance cost. Consult with your insurer before making any significant changes.
Taming the Insurance Beast: Strategies to Save
Understanding how car insurance companies operate empowers you to find ways to save. Here are some strategies to consider:
- Comparison Shop: Don’t settle for the first quote you receive. Get quotes from multiple insurers to find the best rate.
- Maintain a Clean Driving Record: Avoiding accidents and traffic violations is the golden rule for keeping your premiums low.
- Increase Your Deductible: A higher deductible lowers your premium, but remember you’ll have to pay more out of pocket if you file a claim.
- Bundle Your Policies: Bundling your car insurance with your homeowner’s or renter’s insurance can often lead to discounts.
- Take Advantage of Discounts: Many insurers offer discounts for good students, low-mileage drivers, completing defensive driving courses, and insuring multiple vehicles.
- Review Your Coverage Regularly: As your car ages and your driving habits change, re-evaluate your coverage needs. You might be able to reduce coverage and save money.
Beyond the Savings: Finding the Right Balance
While saving money is important, prioritizing adequate coverage is crucial. Here are some additional considerations:
- Liability Coverage: This protects you if you cause an accident and are responsible for the other driver’s injuries and property damage. Ensure you have sufficient liability coverage to protect your assets in case of a serious accident.
- Comprehensive Coverage: This covers damage to your car from non-collision events like theft, vandalism, fire, or weather events. Consider your car’s value and risk factors when deciding on comprehensive coverage.
- Collision Coverage: This covers damage to your car caused by a collision with another vehicle or object. If your car is older or has a low value, you might consider dropping collision coverage.
Remember, the cheapest option isn’t always the best. Striking the right balance between affordability and adequate protection is key.
The Final Lap: Resources and Next Steps
Understanding car insurance goes a long way in making informed decisions. Here are some resources to help you navigate the world of car insurance:
- Your State Insurance Department: Provides information on insurance requirements and consumer rights in your state.
- National Association of Insurance Commissioners (NAIC): Offers resources and consumer guides on car insurance.
Beyond the controllable: External Factors Affecting Rates
It’s important to acknowledge that some factors influencing your car insurance premium are outside your control. These include:
- Market Fluctuations: The overall insurance market can experience fluctuations based on factors like repair costs and the frequency of accidents.
- Natural Disasters: Areas prone to natural disasters like hurricanes or floods may have higher car insurance rates due to the increased risk of damage.
- Cost of Living: The overall cost of living in your area can indirectly affect your car insurance premium.

The Future of Car Insurance: Technological Advancements
Technology is transforming the car insurance landscape. Here are some emerging trends to watch:
- Telematics: Usage-based insurance programs track your driving habits (e.g., mileage, braking patterns) and offer discounts for safe driving.
- Advanced Driver-Assistance Systems (ADAS): Vehicles equipped with ADAS features like automatic emergency braking may qualify for lower premiums due to the perceived lower risk of accidents.
- Autonomous Vehicles: As self-driving cars become more prevalent, car insurance models will likely need to adapt to this new risk landscape.
Related: DIY or Dealership: When to Tackle Motorcycle Repairs Yourself
Staying Informed: Keeping Up with the Changes
As technology evolves and insurance regulations change, staying informed is crucial. Here are some tips:
- Review Your Coverage Annually: Schedule a yearly review with your insurance agent to ensure your coverage remains appropriate for your needs.
- Stay Updated on Industry Trends: Keep an eye out for new technologies and regulations impacting car insurance.
- Advocate for Fair Pricing: If you believe your car insurance rate is unfair, contact your state insurance department or insurance company for clarification.
By understanding the factors influencing car insurance costs, employing cost-saving strategies, and staying informed, you can navigate the world of car insurance with confidence. Remember, car insurance is an investment in your financial security. By making informed choices, you can ensure you have the right protection on the road without breaking the bank.